Financial planning, one conversation at a time.
Independent financial planning from a Chartered adviser for people across Hampshire and the South of England. It looks across your pensions and tax, your investments and protection, and what you actually want the money to do.
Whole-of-market advice for pre-retirees, retirees, high-earning professionals and business owners. Fees written in plain language and agreed in writing before any work begins. Plans you can actually feel.
If you’ve been meaning to sort this out for months, a short first call is an easy place to begin.
No decision stands alone.
Pay more into your pension and you’ve changed your tax position, which changes what your ISA should be doing, which changes the inheritance tax picture. Each of those can be right on its own and wrong in combination. So I plan the whole, not the part.
Built for 2046.
I’m building a practice you could still be a client of in twenty years’ time. So whatever I recommend today, I’ll still be here to be asked about it, at the point when we both know how it turned out.
Risk warnings
ISAs
The favourable tax treatment of ISAs may be subject to changes in legislation in the future.
Pensions
The value of pensions and any income from them can fall as well as rise. You may not get back the full amount invested.
Pensions
Levels and bases of, and reliefs from, taxation are subject to change and their value will depend upon personal circumstances. Taxation and pension legislation may change in the future.
A pension is a long-term investment and the value is not guaranteed. Any advice or considerations are personal to each individual’s circumstances.
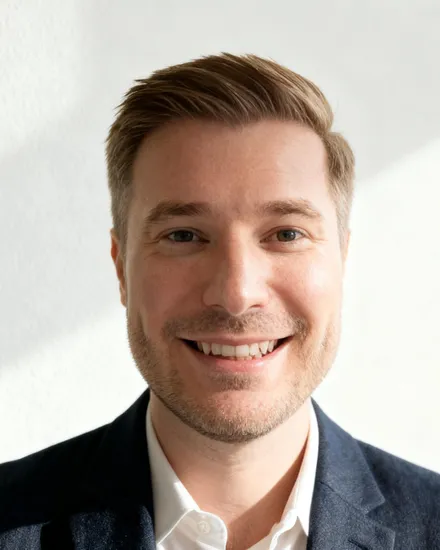
If you’re on this page, you’re probably weighing whether to talk to a financial planner, and whether this one is the right one.
I built Verantis to be the practice I’d want as a client. That meant a deliberately small list, one proper conversation a day, fees written plainly, and advice given in the language you’d use at your kitchen table, not the language regulators write for each other.
It also meant being prepared to tell you what you don’t want to hear. I’d rather have it on a Tuesday afternoon, over coffee, while there’s still time for the answer to matter.
If any of that sounds like the kind of relationship you’d want, the discovery meeting is at our cost. If we’re not a fit, I’ll say so, and I’ll point you somewhere better.
Four kinds of conversation.
Most people arrive at one of these moments. Pick the one that fits, and I’ll meet you there.
Approaching retirement
The date is on the horizon. The question is whether the numbers actually add up, and how to draw an income without unpicking a lifetime of saving.
For pre-retirees →Retired & drawing down
The plan is in motion. The job now is keeping income sustainable and tax-efficient, and adjusting it as the next decade unfolds.
For retirees →High-earning professionals
Pensions, allowances and tax-efficient accounts working as hard as you are. Decisions made deliberately now, not patched together at retirement.
For professionals →Business owners
Extraction, pensions, protection, and when the time comes, an exit that gets you the life the business was meant to fund.
For business owners →Risk warning
A pension is a long-term investment, the value of your investment and the income from it may go down as well as up. Your eventual income may depend upon the size of the fund at retirement, future interest rates and tax legislation.
Five areas. One joined-up plan.
Independent and whole-of-market in every one. Advice that looks across your pensions, ISAs and other accounts together, not just inside each one.
The relationship comes first.
Verantis is built around one properly-held conversation a day, so the advice knows you well enough to be genuinely useful.
One client meeting a day.
If your meeting takes a full day, it takes a full day. Nobody gets rushed.
Chartered, with further qualifications.
Level 6 Diploma in Advanced Financial Advice, plus further qualifications in pension transfers (AF7) and long-term care (CF8).
Cashflow plans, year by year.
Visual projections of your assets, income and spending, built on assumptions we agree and revisit each year. They turn “do I have enough?” from a vague worry into a question you can work through with your own numbers.
Fees agreed in writing first.
Tiered, with the rates, caps and worked examples set out in our disclosure document. I’ll confirm exactly what your case would cost, in writing, before any work begins.
Whole-of-market and independent.
Whole-of-market means I can recommend from across the market rather than from a restricted list. I’m not tied to a parent firm, a panel of providers or an in-house fund range, so the recommendation is whatever the evidence and your situation warrant.
Important information
We do not currently provide advice on transferring out of defined benefit (final salary) pension schemes. If you require this advice, we will provide details of a suitably qualified adviser at a firm with the necessary regulatory permissions who can assist you.
Answers you can read before we talk.
Plain-English guides to the questions that bring most people here. Read them tonight, free and without leaving your name. If one raises a question about your own situation, that’s what a first call is for.
"The first job isn’t the numbers. It’s working out what you actually want your money to do for you, which is a question most people have never been asked properly."
Let’s have a proper first conversation.
A 30-minute introductory call, or the full discovery meeting, both at our cost. The meeting leaves you with a clearer picture of your position, whether we end up working together or not.
Book a first conversation
A 30-minute introductory call to test the water, or the full discovery meeting if you’re ready. Both at our cost, with no obligation to proceed.
Bookings are taken through Calendly. The Privacy Notice (opens in a new tab) explains how your details are used.
Or send a message
Not ready to book? Drop a short note and William will reply personally, usually within one working day.